
Specialist lending for doctors and dentists
Medical Practice Finance for Doctors and Dentists
Buy into the practice, or buy it outright, without putting your family home up as security. Medical practice finance in Australia assesses a practice on its earnings and goodwill, so eligible doctors and dentists can, at some lenders, fund up to 100% of the purchase price and keep their home and cash out of the deal.
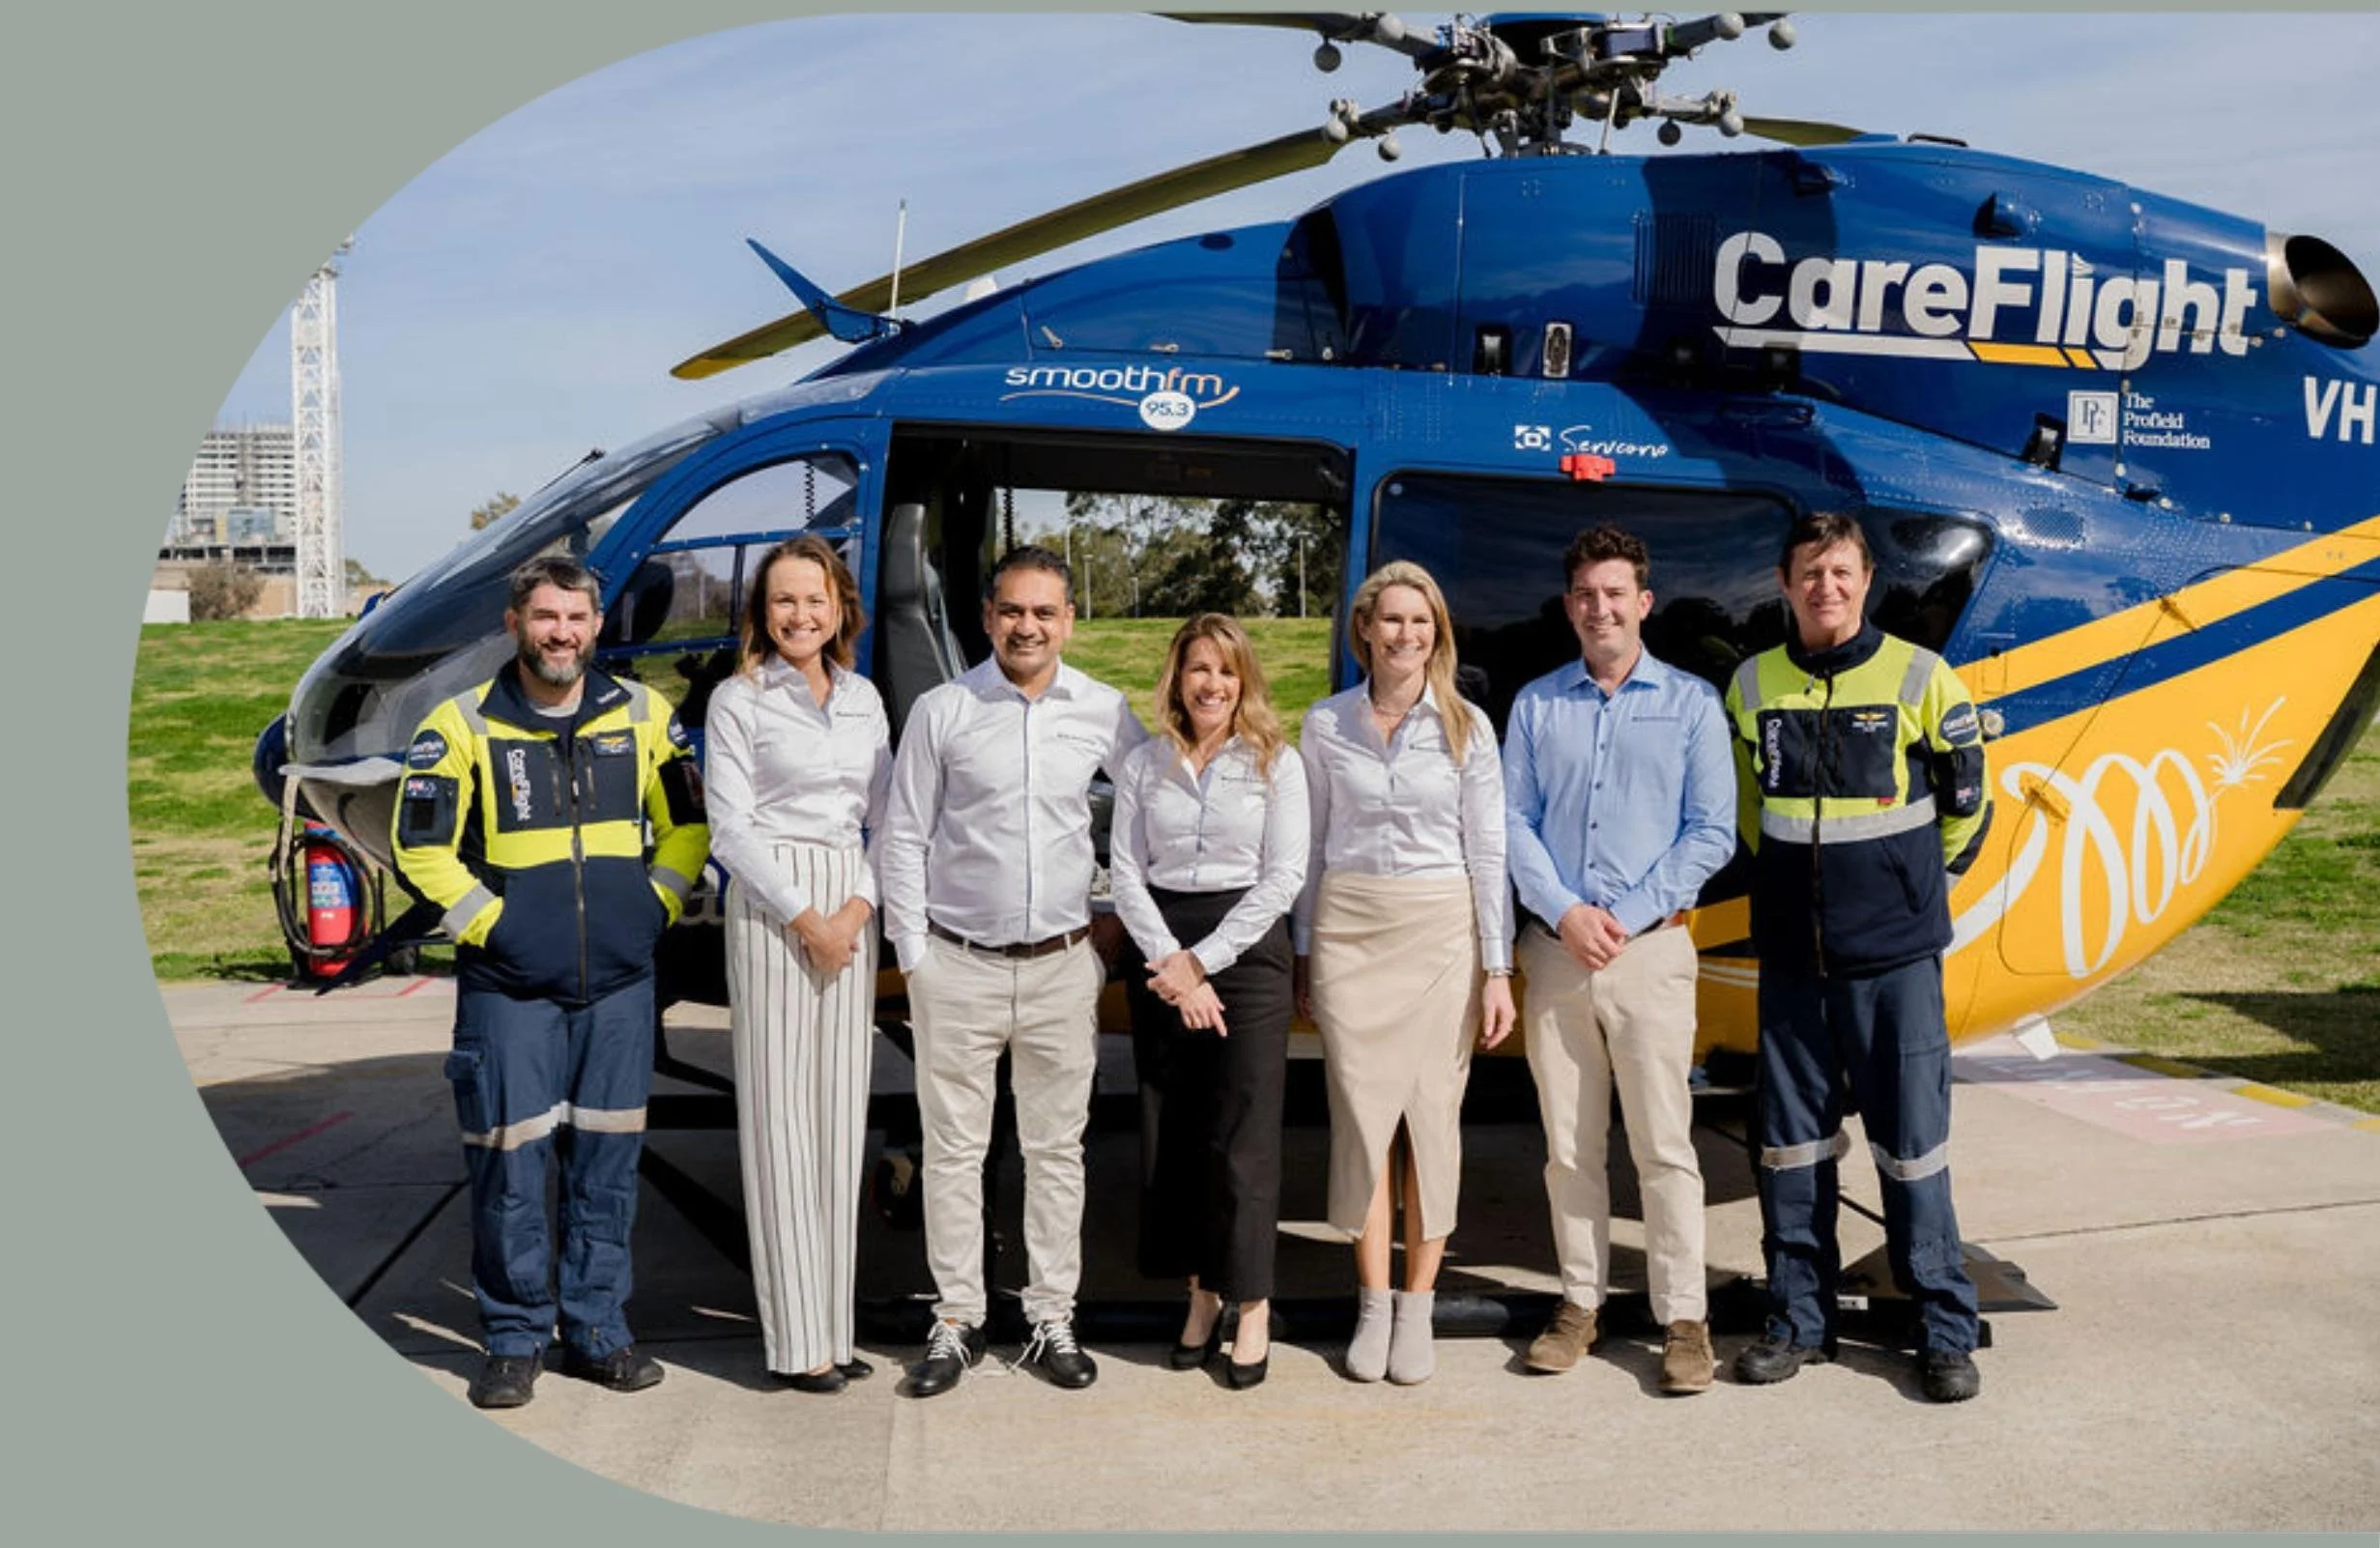

Proudly supporting CareFlight pilot training. Watch highlights from our base visit.
What Practice Finance Covers in Australia
Medical practice finance is commercial lending for buying, buying into or expanding a practice, assessed on the practice's earnings and goodwill instead of the physical assets a home loan relies on.
Because much of a practice's value is goodwill, specialist lenders can secure the loan against the practice and its equipment, so eligible medicos keep the family home out of it. Arranged through a commercial lending broker, the deal is matched to the bank, non-bank and medico-only lenders that write this business.
The premises and the fit-out are funded separately, on their own terms. Where you want to hold the rooms in super, you can hold premises in super as a business-real-property purchase, and buying a pharmacy follows state ownership rules covered on its own page.
How much a lender will fund, and on what terms, depends on the practice's financials, your profession and the structure of the deal, so the numbers are confirmed for your transaction.
Ways to Fund a Practice
A practice deal takes one of four shapes, each funded on its own terms:
Partnership Buy-In
Fund an equity share in an existing practice. Some lenders fund up to 100% of the partnership buy-in for eligible medicos, using the practice as security. This suits an associate offered a stake.
Practice Acquisition
Buy a practice as a going concern, including its goodwill. A practice acquisition is assessed on the earnings history under the current owner. This suits a buyer taking over an established solo or group practice.
Partner Buy-Out
Fund a departing owner's exit so the practice stays intact. The remaining owners take on the share and the debt tied to it. This suits partners whose colleague is retiring or leaving.
New Practice Setup
Fund the working capital and costs of opening a practice from scratch. With no trading history, lenders lean on your contracts, projections and registration. This suits a clinician starting out on their own.
Which structure fits, and how much a lender will fund, depends on the practice and the deal, so treat these as a general guide.
What Lenders Assess
Because the value sits largely in goodwill, lenders weigh the practice and you together:
Practice Earnings
The trend in earnings and cash flow is the core of both goodwill value and the ability to service the loan.
Current Registration
Current registration with the Australian Health Practitioner Regulation Agency (AHPRA) and your profession, since medical professionals are treated as lower-risk borrowers.
Clinical Role
Your experience and your role in the practice, and whether you can sustain the earnings the loan relies on.
Deal Structure
How goodwill, premises and equipment are split across facilities, which affects both the rate and the security.
What a lender counts and how much it lends vary by lender and deal and can change, so treat these as a general guide.
How a Practice Deal Comes Together
The steps run in order, from first contact to settlement:
- Deal review. We look at the practice, the price and how the purchase fits your wider position.
- Accountant coordination. Goodwill valuation and structure sit with your accountant, and we work alongside them.
- Lender match. We compare bank, non-bank and medico-only lenders on lend ratio, term and rate, then shortlist.
- Facilities and approval. We split goodwill, premises and equipment into separate facilities where that is cleaner, and move to approval.
- Settlement. The purchase completes, and we stay available as the practice grows.
Timeframes depend on the lender, the practice and your accountant, so the stages above are a general guide.
Trade-Offs of Practice Finance
Goodwill lending opens terms a general bank will not, at a cost worth weighing:
Where It Helps
Some lenders fund up to 100% of the price against goodwill and equipment, so your home and cash stay out of the deal, and interest-only periods of up to about three years ease the early ramp-up. A specialist reads a practice on its earnings, not on the bricks a home loan would want.
Where It Costs
Goodwill lending is priced higher than a home loan, and a general bank may still want the family home and quote 70% to 80%. The debt is largest in the first 12 to 24 months when trading history under your ownership is shortest, and lenders usually require a personal guarantee.
Who Practice Finance Suits
It tends to suit a registered doctor, dentist or specialist buying into or acquiring an established practice with clean financials. It suits less well a practice with no trading history, or a buyer who wants no personal guarantee, which most lenders still require on this lending.
Practice Ownership Without Your Home as Security
The question that stops most buyers is security, and the answer is that a well-run practice can usually stand on its own goodwill and equipment, keeping your home out of the deal. Whether yours does comes down to its financials and the medico lenders active in Australia, and that is what we confirm before you sign a contract.
Frequently Asked Questions (FAQs)
Can I buy a practice without using my home as security?
Often yes. Specialist medico lenders can secure the loan against the practice's goodwill and equipment, and some fund up to 100% of the price for eligible borrowers. The structure depends on the practice, the deal and the lender.
How is practice goodwill valued?
Goodwill reflects the patient base, reputation and future earnings, and is usually assessed on an earnings multiple or a share of gross revenue. Use an accountant who understands medical and dental practices, so you neither overpay nor miss a warning sign.
Can I fund a buy-in to a partnership?
Yes. Funding an equity share is a common use of practice finance, and some lenders fund up to 100% of the buy-in for eligible medicos. We match you to a lender comfortable with the practice and your position.
Do I need to give a personal guarantee?
Usually yes. Most lenders require a personal guarantee on practice lending, even where the loan is secured against the practice rather than your home. The terms depend on the lender and the deal.
How long can the loan run?
Terms commonly run up to around 15 years, with interest-only periods of up to about three years while you build billings. The exact term depends on the lender and the structure.
Do you arrange the premises and fit-out too?
Yes, usually as separate facilities alongside the purchase. Premises can be held in super as business real property, and the fit-out and equipment are funded on their own terms.
Why use Specialist Broking instead of going directly to my bank?
A general bank often reads a practice like any small business, wants the family home as security and quotes a lower loan-to-value ratio. We take the deal to the bank, non-bank and medico-only lenders that assess a practice on its goodwill, and coordinate with your accountant. We confirm how we are paid before any work begins.
Who leads the healthcare lending work at Specialist Broking?
Daniel Jones, founder and chief executive, began his finance career at Medfin Finance, supporting doctors, dentists and allied health professionals, before founding Specialist Broking. The team works with medical professionals across home lending, refinancing, and practice and equipment finance.
How do I get started?
A free 15-minute consultation is the starting point, available through the Specialist Broking website, by phone on +61 423 308 892, or by email at daniel@specialistbroking.com.au.
This page provides general information only and does not take into account your objectives, financial situation or needs. It is not taxation, accounting or financial advice. Lending criteria, rates and terms vary between lenders and can change without notice, and a practice deal depends on the practice's financials and your circumstances. Consider speaking with a qualified professional before acting.

OUR SPECIALIST AREAS
We believe finance should be delivered with care, integrity and expertise, by people who know what it’s like to stand in your shoes.
-
Daniel Jones, Founder and CEO, is a former commercial pilot who understands aviation finance: variable rosters, unique allowances and banks that don’t always get a pilot’s income.
-
Our team supports doctors, dentists and allied health professionals with finance strategies that evolve throughout their careers, from buying a first home to growing a practice and building long-term wealth.
-
Our finance capability runs deep across commercial and investment lending. Led by Daniel Jones, who has worked extensively in medical and professional finance, our team structures lending that supports business growth, cash flow and asset acquisition.
-
We know finance is never just about numbers. It is about decisions that shape homes, careers and futures. We support first home buyers, families planning their next move and clients looking to refinance or consolidate debt.
Our Team

CEO and Founder
A former Qantas Group pilot turned specialist broker, Daniel helps aviation, medical and business professionals navigate complex finance with precision. He builds long term relationships with clients, helping them strengthen their financial position and plot a course that makes sense for the long haul.

Specialist Broker
Carly helps clients turn property goals into reality by combining her experience in Sydney's property market and global finance with practical lending advice tailored to each client's circumstances.
How we work
Together, our team helps clients structure lending that is strategic, adaptable and built for the long haul.
STEP 1
Reach out to Specialist Broking.
STEP 2
We get to know you and your goals.
STEP 3
We negotiate with banks and lenders.
STEP 4
We conduct an annual financial health check.
WHAT OUR CLIENTS SAY:
“We had an excellent experience with Specialist Broking. Dan assisted us with our home loan and made the entire process straightforward and stress-free.
Dan was consistently professional, approachable, and responsive to our questions. We felt well supported throughout and would not hesitate to recommend Specialist Broking to others seeking a broker.”
Stephanie Knook — Physiotherapist