
Specialist lending for doctors
Medical Refinancing for Doctors
Stop carrying a loan that was set up before your income and your options caught up with it. Medical refinancing in Australia moves you onto profession-based terms you may not have qualified for the first time, and can release equity or unwind a structure that no longer serves you, on the loan you already hold.
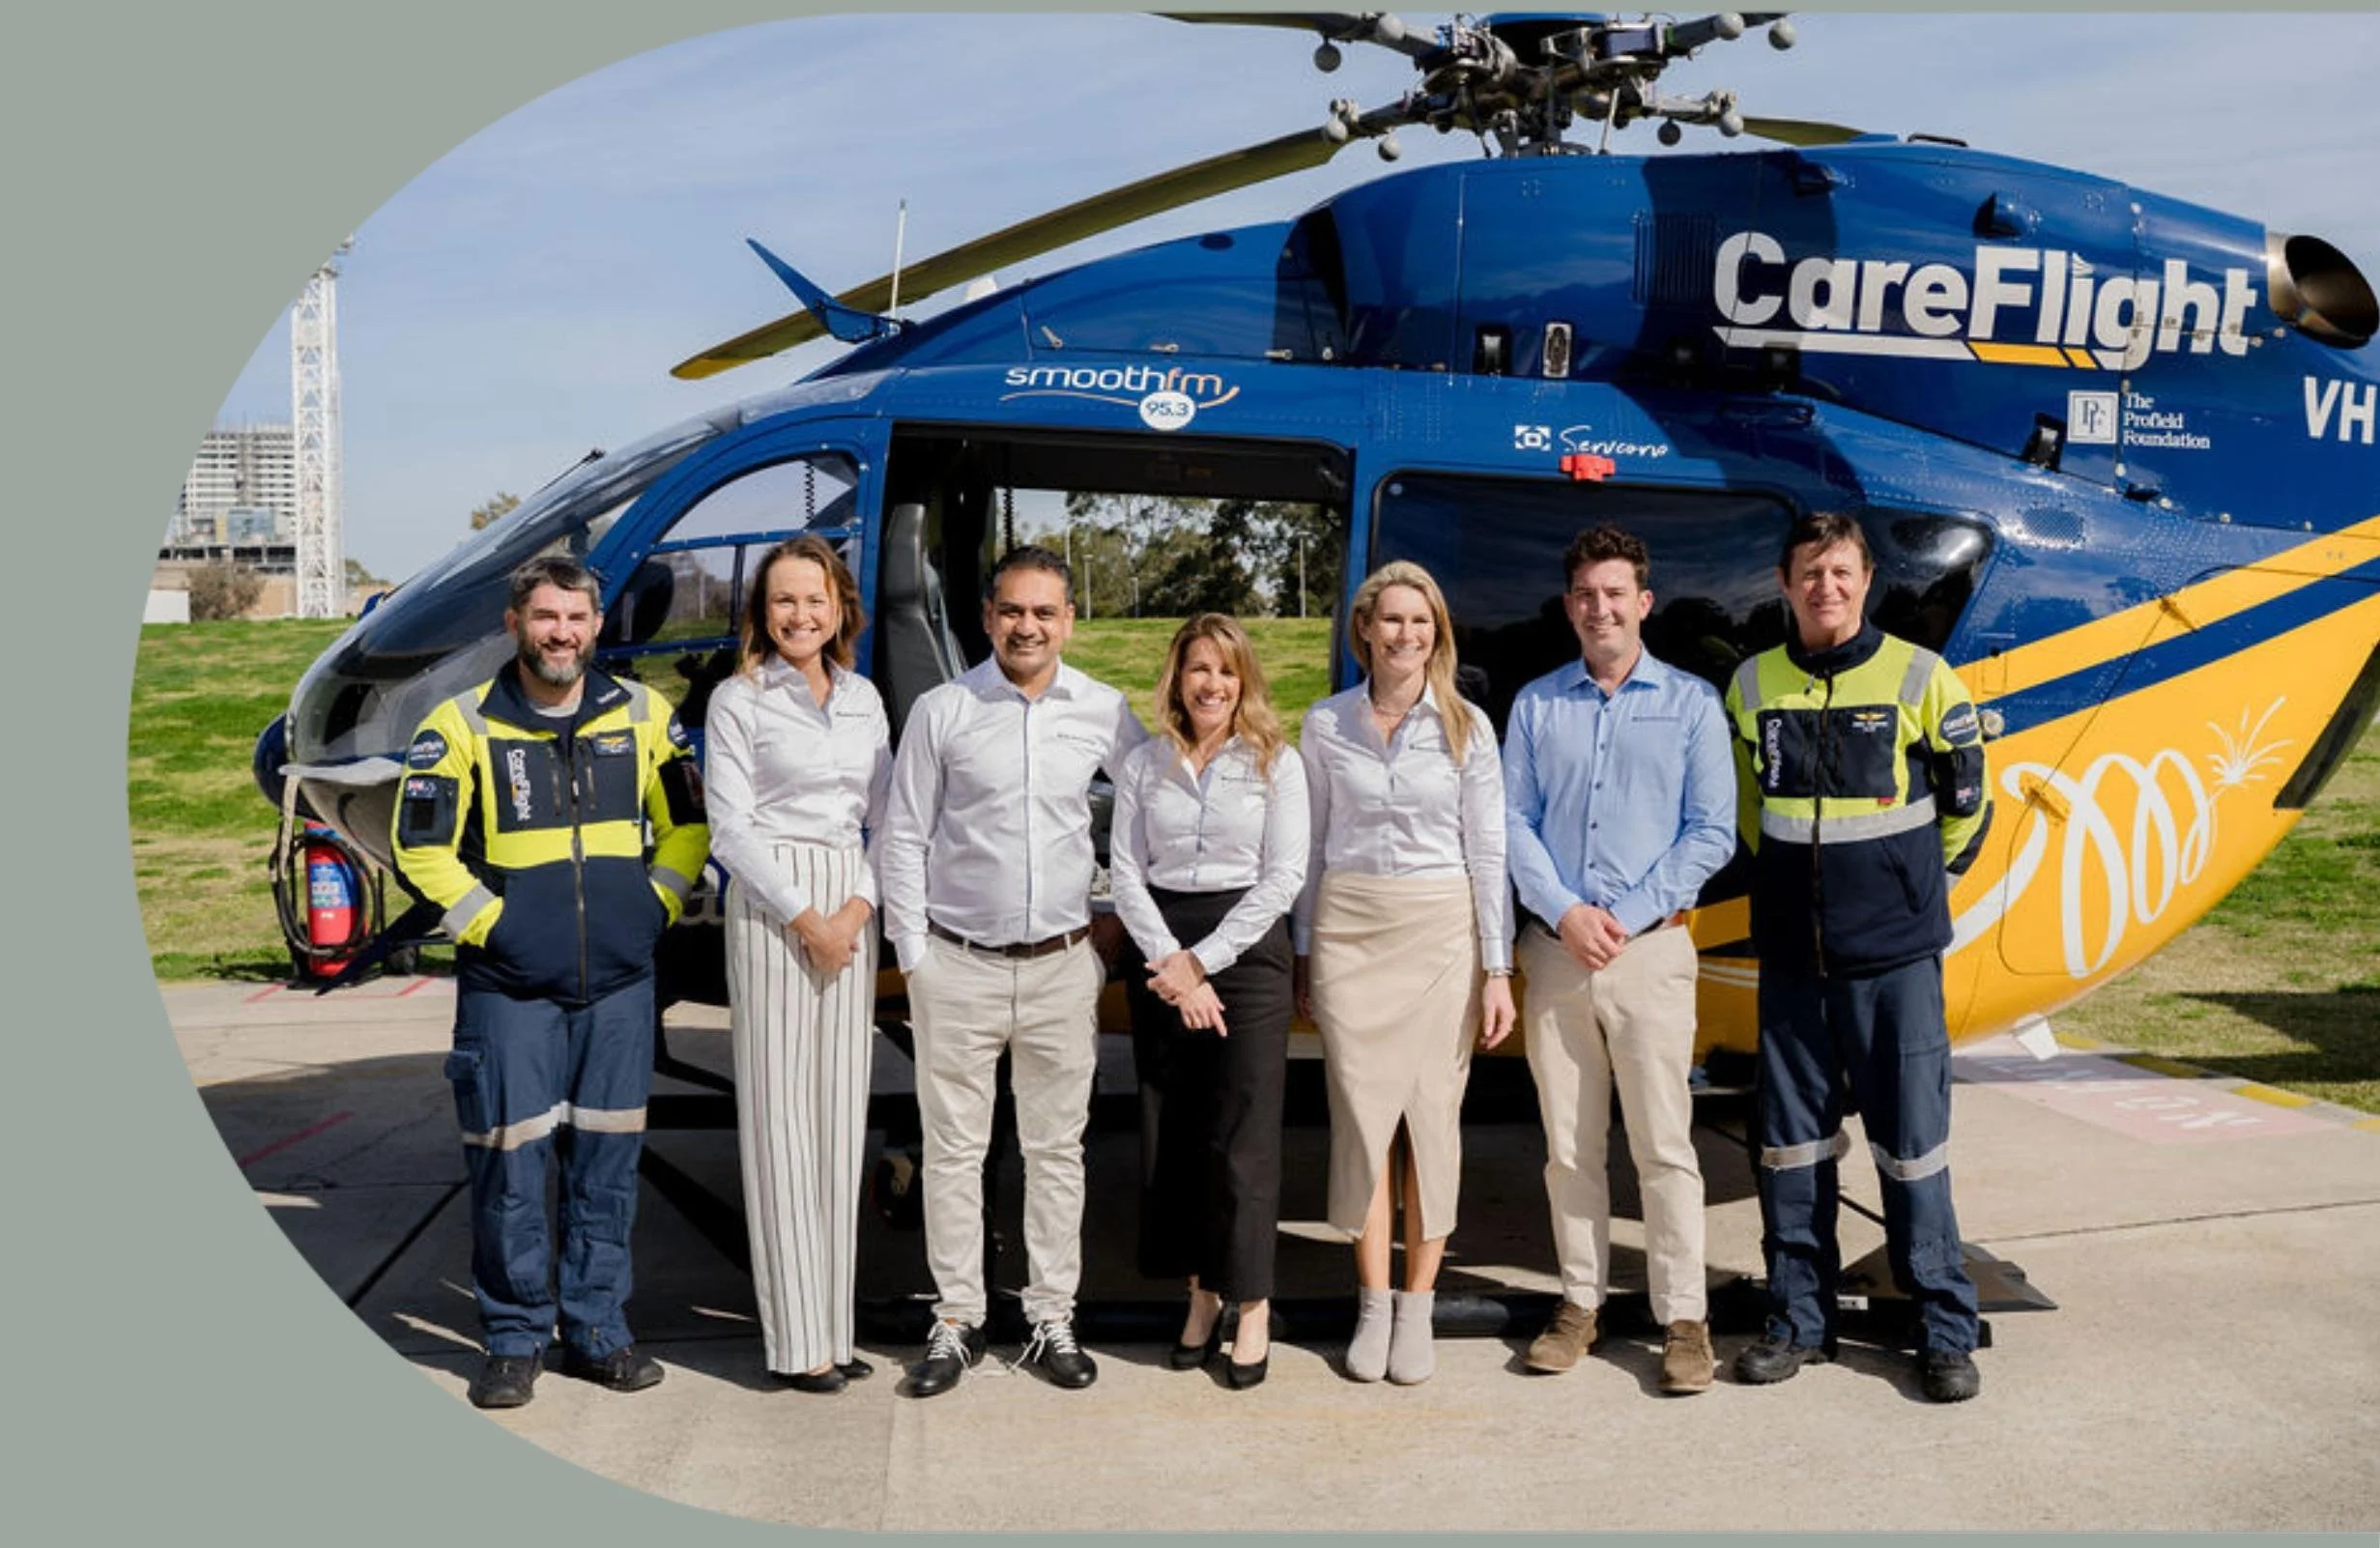

Proudly supporting CareFlight pilot training. Watch highlights from our base visit.
What Refinancing Achieves for Australian Medicos
Refinancing replaces your current loan with a sharper one, and for a doctor the gain is often more than a lower rate. It can mean the medico benefits you could not use the first time, equity you can put to work, or a structure that stops holding you back.
The profession-based benefits a doctor home loan broker can access are not only for a purchase. At many lenders, the same waiver of lenders mortgage insurance (LMI) and pricing apply on a switch, and refinancing through a broker surfaces the lenders whose current policy fits how you earn.
A refinance carries costs as well as savings, so it only makes sense once the new position beats the old one after those costs, which is the first thing we work out with you.
Reasons Medicos Refinance
A switch usually does one of four jobs for a doctor:
Professional Waiver
The LMI waiver you did not use on purchase can apply on the switch at many lenders, which is often the reason a refinance pays for a doctor who bought before qualifying.
Equity Release
You can release equity from a home to fund the deposit on an investment, practice premises or fit-out, without disturbing the rest of your lending.
Loan Restructure
A refinance can separate cross-collateralised loans that tie your properties together, or fix an ownership structure chosen for speed rather than the long term.
Debt Consolidation
Other debts can be folded into the loan to simplify repayments, though spreading a short-term debt over a long term can raise its total cost.
Which job a refinance does, and whether it pays, depends on your loan, your equity and the lender, so treat these as a general guide.
When Refinancing Makes Sense
A switch is usually worth a closer look when:
- your rate sits well above what your profession can access today
- you have equity you want to put toward the next purchase
- your loans are cross-collateralised or the structure limits you
- your circumstances have changed through a new role, a partner or a practice
Whether a switch pays turns on your rate, balance and costs, so treat this as a general guide.
How a Refinance Works
The steps run in order, from review to settlement:
- Review your current loan. We look at your rate, structure and the benefits you can now access.
- Check your eligibility. We confirm which profession-based concessions apply to your position.
- Compare the market. We compare your loan against the lenders most likely to improve it.
- Recommend or hold. If a switch does not put you ahead, we say so; if it does, we set out the numbers.
- Manage the switch. We handle the application, discharge and settlement.
Timeframes depend on the lender and your paperwork, so the stages above are a general guide.
Trade-Offs of Refinancing
A switch can pay well, and it does not always, so both sides are worth weighing:
Where It Helps
It can apply the medico benefits you missed, free equity for the next step, fix a structure that limits you, and lower your repayments. On a large loan, the waiver and pricing alone can be worth switching for.
Where It Costs
Exit, discharge and setup costs have to be recovered before you are ahead, and stretching the loan back out over a longer term can raise the total interest even at a lower rate. A small rate gap may not cover the switch, and releasing equity adds to the debt.
Who Refinancing Suits
It tends to suit a doctor whose loan predates the medico benefits, who has equity to put to work, or who is held back by the current structure. It suits less well someone early in a fixed term with high break costs, or where the savings would not cover the cost of switching.
Terms You Would Choose Today
A loan set up years ago is rarely the one you would choose now, and the only way to know if a switch pays is to run your numbers against the market in Australia. We do that first, and if refinancing does not put you ahead, we say so before you move.
Frequently Asked Questions (FAQs)
Can I get an LMI waiver when I refinance?
Possibly. Many lenders extend the medico LMI waiver to a refinance, not only a purchase, for eligible professionals. Eligibility depends on your profession, income and the lender's current policy.
Will refinancing hurt my credit?
A refinance involves a credit enquiry, as any application does, and the effect is usually minor for a borrower with a sound history. The question that matters more is whether the new loan improves your rate, structure or flexibility enough to be worth the switch.
Can I refinance to release equity for an investment or practice?
Often yes. Releasing equity from a home is a common way to fund the deposit on an investment property or practice premises. We structure the release so it supports the next purchase rather than stretching your position.
How is my HECS-HELP debt treated on a refinance?
Lenders count the compulsory HECS-HELP (Higher Education Loan Program) repayment as a committed expense in most serviceability assessments. Since late 2025, some lenders can set it aside where the balance is close to being cleared, which can help. The effect depends on your balance and the lender.
Is it worth refinancing for a small rate difference?
Not always. The saving has to cover the exit, discharge and setup costs before you are ahead. Sometimes the stronger reason to refinance is structure or equity access rather than rate, and we model the real position before you decide.
Why use Specialist Broking instead of going directly to my bank?
Your current bank has little reason to offer its sharpest terms to keep you. We compare the market against how you are paid and which profession-based benefits now apply. For residential loans, our fee is generally paid by the lender at settlement, not by you.
Who leads the healthcare lending work at Specialist Broking?
Daniel Jones, founder and chief executive, began his finance career at Medfin Finance, supporting doctors, dentists and allied health professionals, before founding Specialist Broking. The team works with medical professionals across home lending, refinancing, and practice and equipment finance.
How do I get started?
A free 15-minute consultation is the starting point, available through the Specialist Broking website, by phone on +61 423 308 892, or by email at daniel@specialistbroking.com.au.
This page provides general information only and does not take into account your objectives, financial situation or needs. It is not financial advice. Lending criteria, rates and concessions vary between lenders and can change without notice, and whether a refinance suits depends on your circumstances. Consider speaking with a qualified professional before acting.

OUR SPECIALIST AREAS
We believe finance should be delivered with care, integrity and expertise, by people who know what it’s like to stand in your shoes.
-
Daniel Jones, Founder and CEO, is a former commercial pilot who understands aviation finance: variable rosters, unique allowances and banks that don’t always get a pilot’s income.
-
Our team supports doctors, dentists and allied health professionals with finance strategies that evolve throughout their careers, from buying a first home to growing a practice and building long-term wealth.
-
Our finance capability runs deep across commercial and investment lending. Led by Daniel Jones, who has worked extensively in medical and professional finance, our team structures lending that supports business growth, cash flow and asset acquisition.
-
We know finance is never just about numbers. It is about decisions that shape homes, careers and futures. We support first home buyers, families planning their next move and clients looking to refinance or consolidate debt.
Our Team

CEO and Founder
A former Qantas Group pilot turned specialist broker, Daniel helps aviation, medical and business professionals navigate complex finance with precision. He builds long term relationships with clients, helping them strengthen their financial position and plot a course that makes sense for the long haul.

Specialist Broker
Carly helps clients turn property goals into reality by combining her experience in Sydney's property market and global finance with practical lending advice tailored to each client's circumstances.
How we work
Together, our team helps clients structure lending that is strategic, adaptable and built for the long haul.
STEP 1
Reach out to Specialist Broking.
STEP 2
We get to know you and your goals.
STEP 3
We negotiate with banks and lenders.
STEP 4
We conduct an annual financial health check.
WHAT OUR CLIENTS SAY:
“As an ophthalmologist, my financial situation is a mix of personal and business considerations, and I needed advice that genuinely understood both.
Dan took the time to really get across how my practice operates as well as my personal goals, and helped structure solutions that made sense across home lending and practice setup.”
Hamish Dunn — Opthalmologist